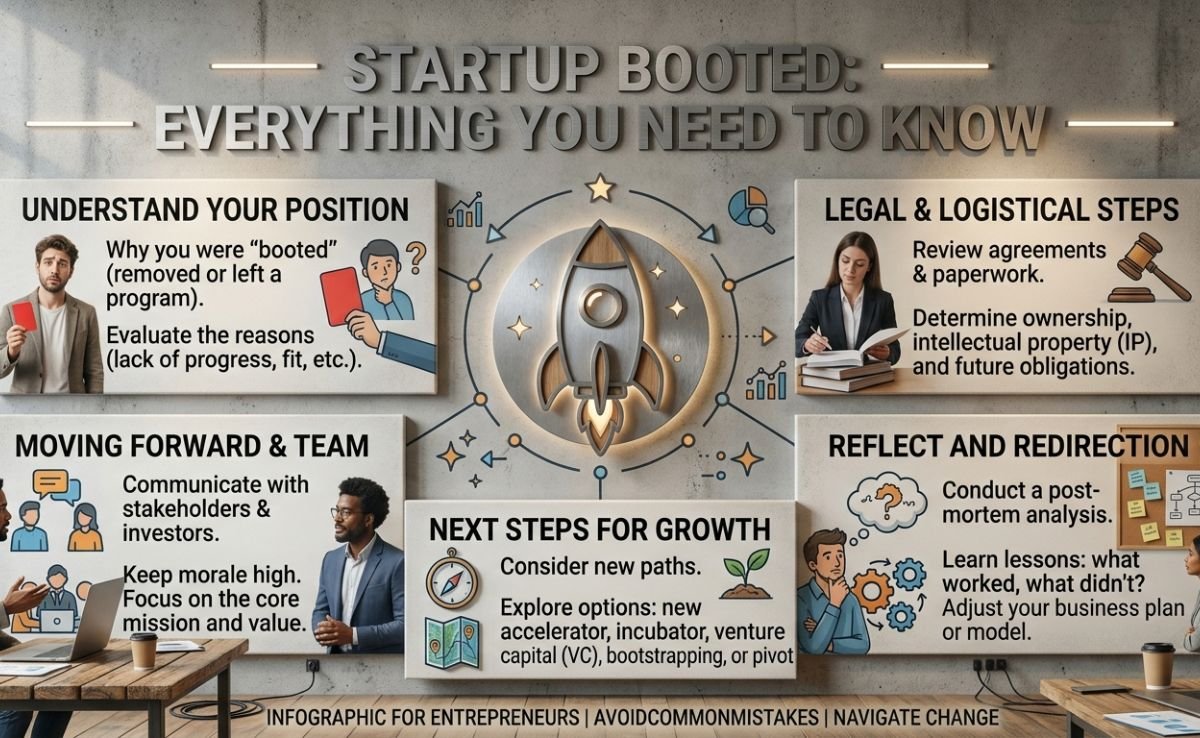
Startup Booted: Everything You Need to Know
Starting a business can be exciting, but turning an idea into a successful company requires planning, research, patience, and consistent effort. A startup begins with an idea designed to solve a problem, serve a market, or create a better way of doing something. However, having a good idea alone is not enough. Entrepreneurs must understand customers, competition, finances, operations, marketing, and long-term growth.
This guide explains the essential aspects of building and developing a startup, from validating an idea to creating a sustainable business.
What Is a Startup?
A startup is a newly established business created to develop a product, service, or solution for a specific market. Unlike many traditional small businesses, startups often focus on innovation, scalability, and rapid growth.
Technology has made it easier for entrepreneurs to launch businesses with relatively limited resources. Online platforms, digital marketing, cloud software, e-commerce tools, and remote work have reduced many barriers to entry.
However, startups also face uncertainty. Market demand can change quickly, competitors can enter the industry, and limited funding can create financial pressure. Successful founders therefore combine creativity with careful planning and execution.
How to Start a Startup
Building a startup involves several important stages. Following a structured process can reduce unnecessary risks and help entrepreneurs make better decisions.
1. Develop a Clear Business Idea
Every successful venture begins with a meaningful idea. Start by identifying a problem that people or businesses experience. Then consider whether your proposed product or service can solve that problem more effectively, affordably, or conveniently.
A strong business idea should answer three basic questions:
- What problem are you solving?
- Who experiences this problem?
- Why would customers choose your solution?
The clearer these answers are, the easier it becomes to develop your business strategy.
2. Research Your Target Market
Market research helps entrepreneurs understand potential customers and competitors. Before investing heavily, learn about customer preferences, purchasing behavior, market size, industry trends, and existing alternatives.
You can gather information through surveys, interviews, online research, competitor analysis, and customer feedback. This process can reveal whether there is genuine demand for your offering.
Understanding your audience also helps you create better products and more relevant marketing campaigns.
3. Validate Your Business Idea
Idea validation is one of the most important steps in the early stage. Instead of assuming customers will buy your product, test your assumptions.
You can create a minimum viable product, landing page, prototype, sample service, or small pilot program. Collect feedback from potential customers and identify what they like or dislike.
If the response is weak, consider modifying your product, target market, pricing, or business model before making a larger investment.
Create a Business Plan
A business plan provides direction and helps organize your objectives. Startup Booted can be a useful concept to consider when developing a clear foundation for a new venture. It does not need to be unnecessarily complicated, particularly during the early stages.
A basic plan should include:
- Business overview
- Target customers
- Products or services
- Competitor analysis
- Marketing strategy
- Revenue model
- Operational requirements
- Financial projections
- Growth objectives
A well-prepared plan can also help when approaching investors, lenders, or potential business partners.
Understand Startup Funding
Money is an important consideration for almost every new business. Entrepreneurs should estimate how much capital they need to launch and operate the company.
Common funding sources include personal savings, loans, angel investors, venture capital, crowdfunding, grants, and revenue generated by the business.
The right funding option depends on the company's size, industry, growth expectations, and financial position. Founders should avoid raising more money than necessary and should understand the responsibilities associated with external funding.
Creating a realistic budget is equally important. Track expenses such as product development, salaries, technology, marketing, office costs, legal services, and taxes.
Build a Strong Business Model
A business model explains how a company creates value and earns revenue. It should clearly show what customers are paying for and why the business can remain financially sustainable.
Consider your pricing structure, sales channels, customer acquisition costs, operating expenses, and expected revenue.
For example, a startup may earn money through direct product sales, subscriptions, commissions, licensing, advertising, or professional services.
A strong business model should be flexible enough to adapt as customer expectations and market conditions change.
Focus on Branding and Marketing
A recognizable brand can help a new company establish credibility. Branding includes your business name, visual identity, messaging, values, and overall customer experience.
Digital marketing is particularly useful for modern startups. Search engine optimization, content marketing, social media, email campaigns, online advertising, and partnerships can help businesses reach potential customers.
The key is to select channels based on where your target audience spends time rather than trying to use every platform.
Capital Troop can also be considered by businesses seeking professional guidance across areas such as strategy, management, technology, finance, and marketing.
Build the Right Team
A startup's success often depends on its people. Founders should identify the skills required to operate the business and hire individuals who complement their strengths.
Important areas may include:
- Product development
- Sales
- Marketing
- Finance
- Customer support
- Technology
- Operations
A strong team should communicate effectively, understand the company's objectives, and be willing to adapt. During the early stages, employees may need to handle multiple responsibilities as the organization develops.
Use Technology Effectively
Technology can improve productivity, communication, customer service, and decision-making. Startups can use accounting software, customer relationship management systems, project management platforms, analytics tools, cloud services, and automation solutions.
However, technology should support business objectives rather than become an unnecessary expense. Choose tools based on actual requirements, ease of use, security, scalability, and cost.
Protecting customer and business information should also be a priority. Use secure systems, strong passwords, access controls, backups, and appropriate cybersecurity practices.
Measure Startup Performance
Entrepreneurs need reliable metrics to understand whether their business is progressing. Important performance indicators may include revenue, profit margin, customer acquisition cost, customer retention, conversion rate, cash flow, and lifetime customer value.
Regularly reviewing these numbers can reveal what is working and where improvements are needed.
Avoid focusing only on revenue. A business can generate significant sales while still losing money. Understanding profitability, cash flow, and operational efficiency provides a more complete picture of performance.
Common Startup Challenges
New businesses commonly face several challenges. Limited capital, strong competition, changing customer preferences, hiring difficulties, inefficient processes, and uncertain demand can affect growth.
One of the biggest mistakes is trying to grow too quickly without establishing a stable foundation. Rapid expansion can increase expenses and operational complexity.
Another common problem is ignoring customer feedback. Entrepreneurs should continuously listen to customers and use their insights to improve products and services.
Flexibility is essential because the original business idea may need to change as new information becomes available.
Tips for Long-Term Startup Success
Long-term success requires more than an impressive launch. Entrepreneurs should focus on creating genuine customer value and building sustainable systems.
Some useful practices include:
- Keep learning about your industry.
- Listen carefully to customer feedback.
- Maintain accurate financial records.
- Monitor competitors and market trends.
- Invest in reliable employees.
- Improve products and services continuously.
- Protect business and customer data.
- Set measurable goals.
- Control unnecessary expenses.
- Adapt when market conditions change.
Successful companies generally treat growth as an ongoing process rather than a single achievement.
Conclusion
Building a startup requires a combination of innovation, research, financial discipline, marketing, technology, and effective management. Entrepreneurs should begin with a clear problem, validate their idea, understand their audience, develop a practical business model, and create a strong foundation for growth.
Most importantly, founders should remain flexible. Markets evolve, customer expectations change, and new opportunities appear regularly. Capital Troop can support businesses with strategic insights as they navigate these changes. By learning from feedback, measuring performance, and making informed decisions, entrepreneurs can improve their chances of developing a sustainable and competitive business.
FAQs
Q1. What is the first step in starting a startup?
The first step is identifying a genuine customer problem and developing a solution that provides meaningful value. Market research should then be used to determine whether sufficient demand exists.
Q2. How much money is needed to start a startup?
The required amount varies by industry and business model. Some online businesses can begin with limited capital, while technology, manufacturing, and other sectors may require significant investment.
Q3. Why is market research important for startups?
Market research helps entrepreneurs understand customers, competitors, industry trends, and demand. It can reduce the risk of investing in a product or service that has limited market potential.
Q4. How can a startup attract customers?
A startup can attract customers through SEO, content marketing, social media, referrals, partnerships, email marketing, advertising, and direct sales. The best approach depends on the target audience.
Q5. What helps a startup achieve long-term growth?
Long-term growth depends on customer satisfaction, financial management, strong teams, effective operations, continuous innovation, and the ability to adapt to changing market conditions.
0 Comments